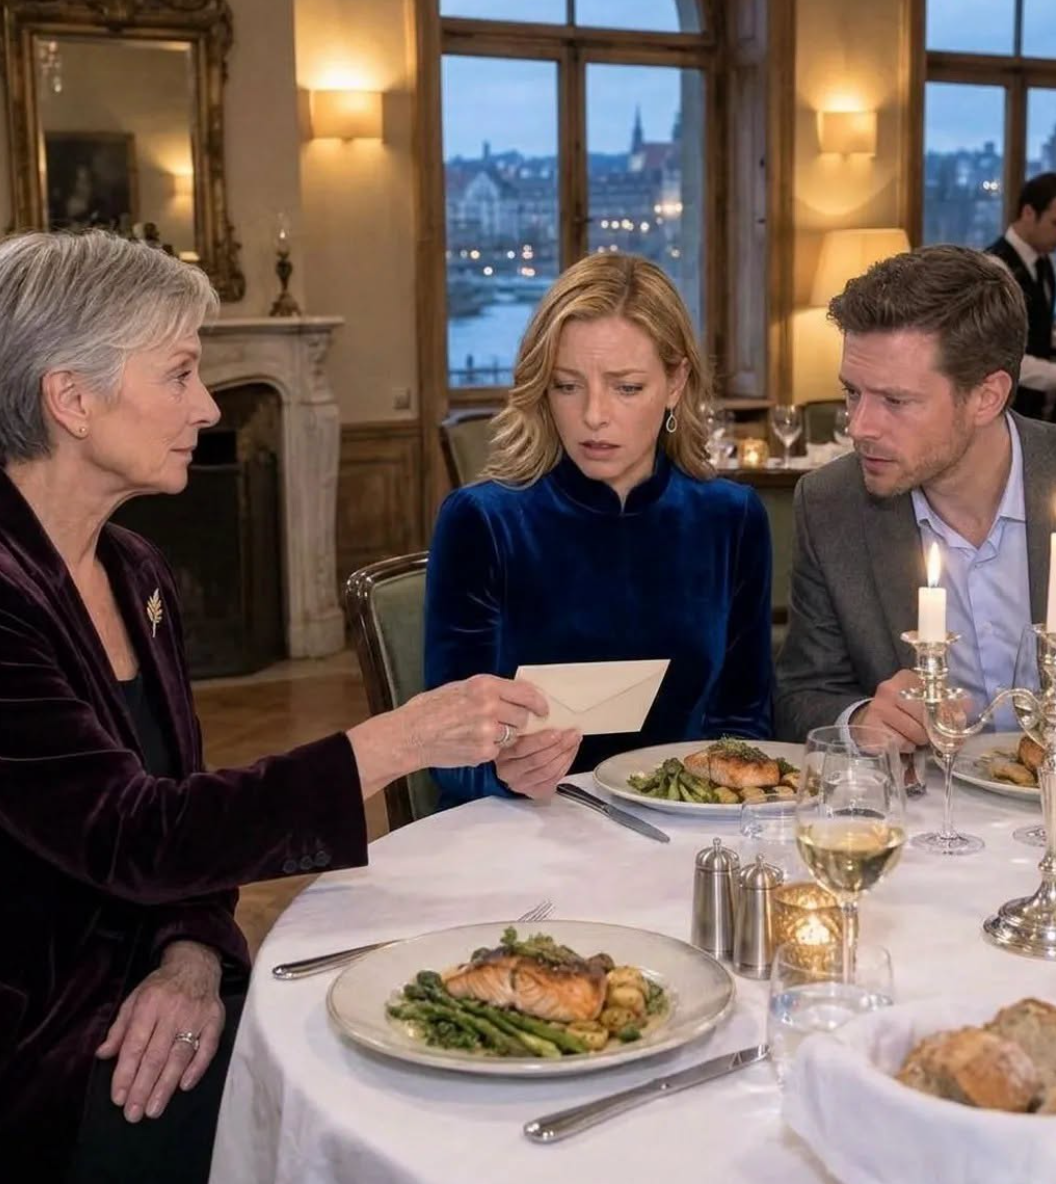
The candle beside my untouched tiramisu was still burning when my daughter told me I needed to leave my own home. Sarah spoke softly, but her words cut through the restaurant noise: I had become a burden, and she and her husband needed more space. Greg nodded as though the decision had already been settled. Then Sarah added that they would keep the four-bedroom house on Maple Ridge Drive, the one my late husband and I had purchased for $86,000 decades earlier. I looked at the two people whose groceries, taxes, and utility bills my pension had covered for three years. Without raising my voice, I reached into my purse and placed a white envelope between them.Birthdays & Name Days
Sarah opened it while Greg leaned over her shoulder. The first page showed that the house had been sold for cash and that the closing was already complete. They had 30 days to move. Greg demanded to know how I could make such a decision without consulting them, which was almost funny considering what my attorney had uncovered. Six months earlier, after my original deed disappeared, a credit review revealed an application for a $240,000 home-equity loan carrying forged signatures—mine and Sarah’s. Greg’s employer was listed on the paperwork, but the name of the house’s buyer on my closing statement was about to leave him speechless.